Most jurisdictions that court digital asset firms arrived at their rules the same way. A securities law was written for shares and bonds, a payments law was written for banks, and then, somewhere between 2018 and 2024, a separate virtual asset regime was bolted on to the side of both. The Gelephu Mindfulness City did not do that. When the GMC Authority enacted its Financial Services Act in 2025, virtual assets, fiat-referenced tokens and spot commodities were already inside it, in the same schedule of regulated activities as deposit-taking and insurance. That is the first argument. There are nine more, and some of them have nothing to do with law. A founder who moves a company also moves a family, a team and a way of living, and GMC is unusual in being a good answer to both questions at once.
In short
- The Financial Services Act 2025, GMC's primary financial services statute, treats virtual asset activity as regulated activity in its own right rather than as an annex to a conventional securities regime.
- One regulator, the Gelephu Financial Services Office, licenses and supervises banks, insurers, fund managers, exchanges and custodians alike. There is no separate crypto authority to coordinate with.
- The rulebooks are not experimental. GMC's Application of Laws Act imports the Abu Dhabi Global Market financial services rulebooks, modified for GMC, and Singapore common law for everything the statutes do not cover.
- The currency of the statute book is the United States dollar. Every dollar sign in the Companies Act and the Income Tax Act means USD.
- The headline corporate rate is 15%, not 0%. The exemptions are real, approval-based and close to new entrants on 31 December 2030. Non-citizen individuals pay 0% to the same date.
- The market has begun to arrive: Matrixport licensed in September 2025, the TER gold token in December 2025, BTSE Bhutan's in-principle approval in May 2026, 3iQ's partnership in July 2026.
- Behind the jurisdiction sits a sovereign that mined bitcoin with hydropower, pledged up to 10,000 BTC to the city, and runs a country that is carbon negative and consistently rated among the least corrupt in Asia.
1. Digital assets were written into the primary statute, not bolted on
GMC is unlike any other jurisdiction a digital asset firm will have looked at. Whether you call yourself a VASP, a CASP, a VDA platform, an exchange, a custodian or a stablecoin issuer, you are reading a financial services statute that had you in mind on the day it was enacted, not one that was amended to tolerate you later. That single fact gives GMC some of the best conditions available anywhere for building a licensed digital asset business, and the rest of this section explains why.
Open Schedule 1 of the Financial Services Act 2025 and you will find one list of specified kinds of activity. Accepting deposits sits there. So does providing custody. So does operating a multilateral trading facility, which the Act defines to include facilities on which financial instruments, virtual assets or spot commodities are traded. The drafters did not create a parallel universe for tokens. They widened the definition of what can be traded on a regulated venue and left the venue rules where they were.
This sounds like a drafting nicety. It is not. It decides three practical questions that consume enormous amounts of counsel time in older centres.
First, perimeter. In a bolted-on regime, firms routinely find themselves arguing that a token is not a security in order to escape one regime and land in another. In GMC, a token that is a virtual asset is regulated activity when someone deals in it, custodies it or runs a venue for it. A token carrying rights amounting to a share or a debt instrument is a specified investment on the same list. Both sit in the same Act, supervised by the same office.
Second, licence architecture. A firm that wants to run an exchange and offer custody does not collect two licences from two agencies under two statutes. It applies for a Financial Services Permission covering the activities it will conduct, and the permission names them.
Third, supervisory consistency. The General Rulebook applies its twelve Principles for Licensed Firms to every licensed firm. A custodian of bitcoin is held to the same standards of client asset protection and systems and controls as a custodian of bonds.
The Financial Services Act names the following among its regulated activities, all of which matter to a digital asset business.
| Activity | Typical crypto business |
|---|---|
| Operating a Multilateral Trading Facility | Spot or derivatives exchange, order book venue |
| Providing Custody | Institutional wallet and key management |
| Arranging Custody | Introducing clients to a custodian |
| Dealing in Investments as Principal or as Agent | Market making, brokerage, OTC desks |
| Issuing a Fiat-Referenced Token | Stablecoin issuance |
| Providing Money Services | Payments, remittance, fiat on and off ramps |
| Managing Assets | Discretionary digital asset portfolio management |
| Managing a Collective Investment Fund | Digital asset funds |
Stablecoins have their own line. The Act defines a fiat-referenced token as a digital asset transferred and stored using distributed ledger or similar technology, whose purpose is to be a medium of exchange with a stable store of value, by referencing a fixed amount of a single fiat currency and enabling the holder to redeem it from the issuer on demand for that amount. Issuing such a token is a specified kind of activity. Very few jurisdictions put stablecoin issuance in primary legislation as a standalone licensable activity rather than in subordinate rules. GMC did.
The perimeter has a hard edge. The same Act prohibits any person from carrying on regulated activity in GMC involving the issue, sale, purchase, transfer or custody of a virtual asset or fiat-referenced token that is an algorithmic stablecoin token, a privacy token, or any digital asset employing similar technology. That is not a rule the regulator may waive on application. It is a statutory prohibition. Firms building around algorithmic pegs or privacy-preserving transfer should treat GMC as closed to them and plan accordingly. There is also an acceptance layer: the regulator may prescribe by rules what makes a virtual asset an accepted virtual asset, so listing decisions are regulatory decisions, not commercial ones.
2. The rulebooks are borrowed from Abu Dhabi Global Market, and the common law from Singapore
A new jurisdiction has one structural problem that money cannot solve quickly. It can hire drafters and publish a statute book in eighteen months. It cannot manufacture the decades of judicial reasoning and supervisory practice that tell a lender what a valid security interest looks like or tell a compliance officer what a regulator expects on a Monday morning. GMC solved this by borrowing rather than inventing.
The Application of Laws Act 2024, GMC's first statute, does three things. It receives Singapore common law, including English common law and the rules of equity as received in Singapore, so far as suited to GMC's circumstances and subject to GMC's own enactments. It applies a schedule of named Singapore statutes, as amended from time to time, with modifications. And it applies a schedule of Abu Dhabi Global Market financial services rulebooks, with references to that centre's regulator reading as GMC's regulator and Islamic finance references removed.
For a digital asset firm this is the single most underrated feature of the jurisdiction. ADGM's framework is one of the most mature virtual asset regimes in the world, and it is the framework your compliance team already knows if you have operated in Abu Dhabi or benchmarked against it. The GEN Rulebook 2026, the anti-money laundering rules, the conduct of business rules and the market rules are recognisable on first reading. Where the applied Singapore law and the applied Abu Dhabi rules conflict, Singapore law prevails for civil and commercial matters unless the GMC Authority decides otherwise. That is a known hierarchy, not a guess.
3. One regulator, one door
Ask any digital asset firm what killed its last expansion and the answer is rarely the licence. It is the sequencing: a regulator that grants approval subject to a bank account, and banks that require a licence before opening an account, with a company registry somewhere in the middle running on its own clock.
In GMC the Gelephu Financial Services Office licenses and supervises banks, insurers, fund managers, exchanges and custodians alike. There is no separate crypto authority whose view has to be reconciled with the securities regulator's view. The application process runs in seven stages, and in-principle approval is stage five: the applicant has satisfied the regulator on business model, controls and people, and now holds a set of pre-conditions, typically incorporation, capital, a bank account, premises and staffing, before a licence issues.
In May 2026 GMC announced an accelerated licensing pathway for firms already licensed in Singapore, Abu Dhabi Global Market or Hong Kong, combining incorporation, regulatory approval and corporate banking into one route. Reported arrangements under the fast-track include multi-currency corporate accounts with DK Bank and fiat-to-crypto rails. Jigdrel Singay, a board director of GMC, framed it as recognising credibility already demonstrated in leading jurisdictions.
It is not passporting. Firms must still comply with GMC's own regulatory standards and supervision. A foreign licence simplifies due diligence. It does not substitute for local review, and it does not authorise anything in GMC by itself. Any adviser who tells you otherwise has read the headline and not the announcement.
4. It is a dollar jurisdiction
Every dollar sign in the GMC statute book means United States dollars. The Companies Act 2025 says so expressly, and the Income Tax Act 2025 sets its bands and rates in USD. Registration fees published by the Gelephu Corporate Registration Office are quoted in USD. Share capital, accounts and tax computations are denominated in the currency most digital asset businesses already report in.
For a treasury team this removes a layer of friction that free zones inside a local-currency country never quite eliminate. There is no conversion at the registry, no local-currency tax computation to reconcile with a USD ledger, and no exchange control question hanging over a stablecoin issuer whose reserve is held in dollars.
5. The tax position is genuinely attractive, once stated correctly
The claim that GMC offers 0% corporate tax has been repeated widely enough that it now needs contradicting in every article on the subject. The Income Tax Act 2025 levies tax on every company or body of persons at 15% on every dollar of chargeable income. That is the headline rate, and by international standards it is a competitive one.
Two approval-based regimes sit beneath it. An approved founders company, carrying on a qualifying business in an industry the designated officer has approved as a founders industry, has that income exempt from tax. The total exemption period, including extensions, cannot exceed fifteen years, and no company may be approved as a founders company after 31 December 2030. Separately, an approved strategic and development company pays a concessionary rate of not less than 5% on income from its specified trade or business, with a relief period capped at twenty years including extensions, and no approvals after 31 December 2030.
So 0% exists. It is discretionary, conditional, time-limited and closing to new entrants at the end of 2030. Individuals who are not citizens of Bhutan pay 0% on chargeable income derived on or before 31 December 2030. Dividends paid by a company resident in GMC are exempt income. Put together, a founder who relocates with the company can, for the next four years, run a business at 15% or better and draw dividends and salary at 0%. That is the window, and it is the reason the next four years are the cheapest GMC will ever be.
6. The market has started to arrive
Regulatory design is a claim. Transactions are evidence. Four dated events are worth recording.
In September 2025, Matrixport received a Financial Services Licence from the GMC Authority and announced it would establish an office in GMC. That was the first signal that the licensing route was not theoretical.
In December 2025, a gold-backed token called TER launched on the Solana network, issued under a sovereign framework with custody provided by DK Bank, described as Bhutan's first licensed digital bank. Days later, the GMC Authority appointed Matrixdock, Matrixport's tokenisation arm, as the key technology provider for TER's tokenisation infrastructure. HB Lim of the GMC Authority put the thesis plainly at the time, saying that GMC aims to be an innovative, transparent and blockchain-centred hub for digital assets, and that regulatory clarity is its competitive edge.
In May 2026, BTSE Bhutan received in-principle approval from the Gelephu Financial Services Office as a Financial Services Licensee for two activities: operating a multilateral trading facility for virtual assets, and providing institutional-grade custody. It was reported as the first exchange approval in the jurisdiction. In-principle approval is the regulator's decision on substance, with a licence following once the pre-conditions are met.
In July 2026, 3iQ Corp, a global digital asset investment manager, announced a strategic partnership with GMC under which it will manage a dedicated mandate backed by a portion of GMC's bitcoin reserves, invest in local talent and establish a long-term operational presence in Gelephu. Jigdrel Singay described it as a first step in building an institutional digital asset management hub. Separately, Bitget has been reported as exploring a licensed hub in GMC.
7. The sovereign understands the asset class
Few governments courting crypto firms have ever held the asset. Bhutan has. A country of fewer than a million people became one of the world's earliest sovereign bitcoin miners, powering the operation with its own hydropower and holding the position through Druk Holding and Investments, the national sovereign wealth fund. On 17 December 2025, Bhutan pledged up to 10,000 BTC, reported at around US$1 billion, from national reserves to support the Gelephu Mindfulness City's development, structured as a long-term sovereign reserve intended to generate yield without selling the assets.
This matters to a crypto company in a way that is easy to underrate. The people who wrote the Financial Services Act, and the people who supervise under it, work for a state that has run mining infrastructure, managed custody at sovereign scale, and now has a reserve mandate managed by an institutional digital asset firm. The conversation with the regulator does not start with an explanation of what a wallet is.
8. Clean power, clean air, and a constitution that protects both
The power base is hydro. Bhutan's grid is built on hydropower, and the same resource that supported state bitcoin mining is what makes a green compute proposition credible for data centres, validators and mining operations that must now answer to investors about their energy source. Green Energy and Technologies is one of GMC's eight priority industries, and it is the pillar where large capital projects are most likely to fit the strategic and development company route.
The environment is not a marketing line. Bhutan's Constitution requires that a minimum of 60% of the country's land remain under forest cover for all time, and the actual figure is comfortably above that. Bhutan is one of the very few countries in the world that is carbon negative: its forests absorb more carbon dioxide than the country emits. A digital asset firm that has spent three years defending its footprint can locate in a jurisdiction where the footprint question is answered by the host country's own balance sheet.
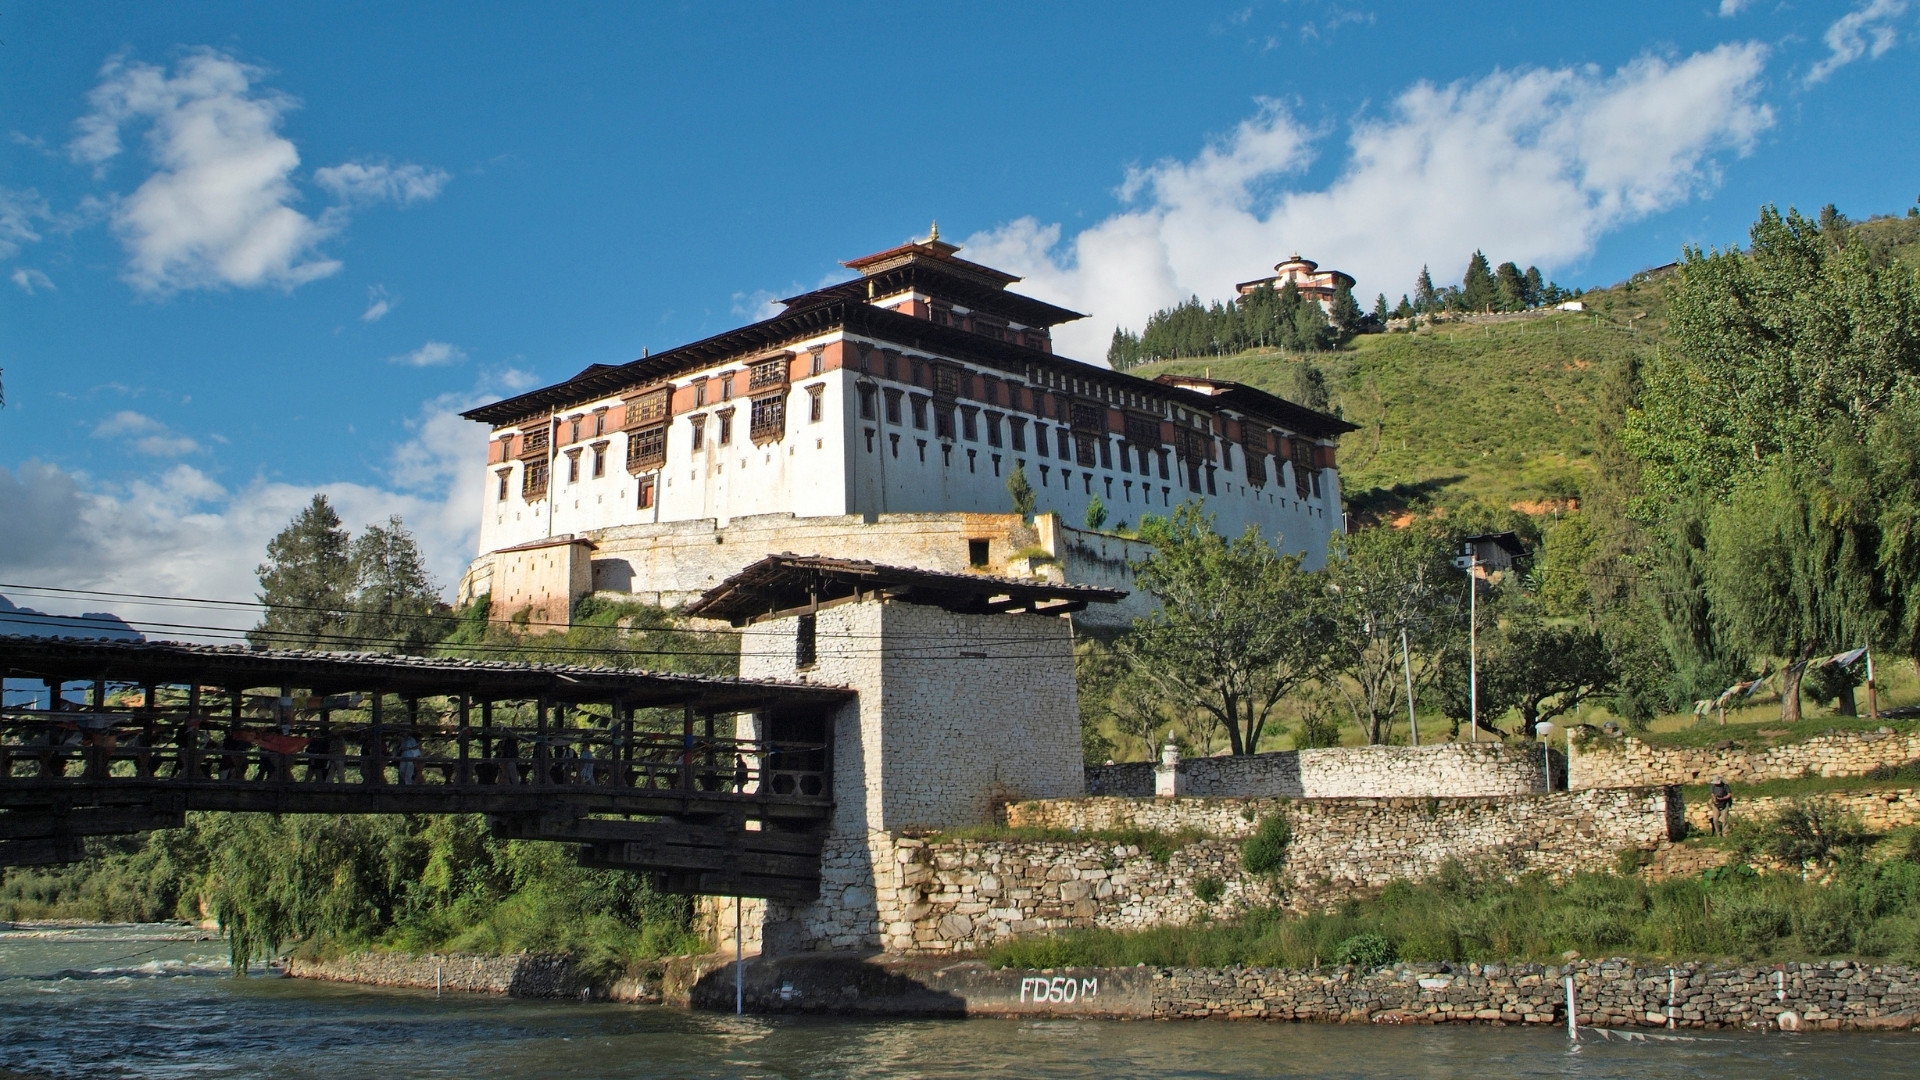
For the people who move, it means something simpler. Gelephu sits in the southern foothills on the Indian border, with forested hills above the plain, and the air is clean in a way that staff relocating from most financial centres will notice in the first week.
9. Low corruption, high trust
Digital asset firms have learned, expensively, that a permissive regulator in a low-integrity state is a liability rather than an asset. Licences that can be bought can also be revoked for a rival, and enforcement that depends on relationships cannot be priced.
Bhutan is the opposite case. Transparency International's Corruption Perceptions Index has, in its most recent editions, placed Bhutan inside the top thirty of roughly 180 countries and first in South Asia, ahead of most of the jurisdictions that digital asset firms currently call home. The GMC framework builds on that foundation: the Royal Charter is granted by the King and can be amended only by Royal Decree, the GMC Authority is chaired by the King, and every Act takes effect with Royal Assent. Continuity of policy is anchored at the very top of the state rather than in a ministry that changes with an election.
Combine that with a statute book you can read in an afternoon, an ADGM-derived rulebook your compliance officer already knows, and a regulator that has publicly said regulatory clarity is its competitive edge, and the result is a jurisdiction where the rules are the rules.
10. It is a place people want to live
Every other reason on this list can be found, in some combination, somewhere else. This one cannot. The Gelephu Mindfulness City was chartered with objectives that pair foreign investment, talent, employment and technology with well-being and mindful living, consistent with Bhutan's philosophy of Gross National Happiness. The masterplan by Bjarke Ingels Group organises a region of roughly 4,046 square kilometres around neighbourhoods shaped by the rivers that cross it, with Gelephu International Airport as the anchor infrastructure and a reported first-phase capacity of about 1.3 million passengers a year.
The eight priority industries say the same thing from the other direction. Finance and digital assets sit alongside spiritual, health and wellness, education and knowledge, agri-tech and forestry, green energy and technologies, aviation and logistics, and tourism. The city is being designed for people to stay, not to fly in for board meetings. For a founder deciding where to spend the next decade, and for the engineers and compliance staff who have to be persuaded to move, a jurisdiction that offers clean air, safety, a mountain culture and a low-stress pace of life, together with 0% personal tax to 2030, is a materially easier sell than another tower in another hub.
Frequently asked questions
Do I need a licence to run a crypto exchange in GMC?
Yes, if you are operating a multilateral trading facility on which virtual assets are traded, by way of business, in GMC. That is a named regulated activity under the Financial Services Act 2025. Order routing systems where interests are merely transmitted and do not interact are excluded.
Can I issue a stablecoin from GMC?
A fiat-backed stablecoin redeemable on demand for a fixed amount of a single fiat currency falls within the Act's definition of a fiat-referenced token, and issuing one is a licensable activity. An algorithmic stablecoin token is prohibited outright.
Does my Singapore or ADGM licence carry over?
No. It may accelerate review under the fast-track pathway announced in May 2026, but the Gelephu Financial Services Office reviews, licenses and supervises locally.
Is crypto trading in GMC tax-free?
No. Companies are taxed at 15% on chargeable income. Exemptions and concessions exist by approval only, and the two principal ones close to new approvals on 31 December 2030. Non-citizen individuals pay 0% to the same date.
What is in-principle approval?
A regulatory decision that the applicant has satisfied the regulator on substance, subject to pre-conditions such as incorporation, capital, premises and staffing. A licence follows once those are met. It is not authorisation to operate.
Is Gelephu actually somewhere my team would live?
It is a city being built to a masterplan, with an airport under way and a legal system already running. The setting is settled: forested hills, clean air, a small and safe country, and a charter that puts well-being alongside investment. Firms relocating staff now are early, and the 0% personal rate to 2030 rewards them for it.
The bottom line
The case for Gelephu is not that it is cheap or permissive. It is that the rules for digital assets were written into the primary financial services statute at the outset, on an ADGM-derived rulebook, in US dollars, under one regulator, in a country that has held the asset itself and is rated among the least corrupt in Asia. Add a tax window that runs to the end of 2030 and a setting people would choose to live in, and the proposition is unusual. GMC courts can rely on common law precedents from any common law jurisdiction, so parties have a settled body of case law from the day the jurisdiction opened. Firms that need a clear statutory perimeter and a regulator that will engage on a novel product should be in the room now, before the 2030 windows close.
This article is general information about the law of the Gelephu Mindfulness City Special Administrative Region as at the date above. It is not legal advice and does not create a lawyer-client relationship.
You may contact Basnet Law at basnet@basnetgmc.com or office@basnetgmc.com for any legal queries related to GMC.
Sources
- Financial Services Act 2025 (Law No. 5 of 2025): s. 5A (rules for virtual assets, fiat-referenced tokens and spot commodities; prohibition on algorithmic stablecoin tokens and privacy tokens at s. 5A(4)); s. 5B (general direction power); Schedule 1 Part 2 paragraphs 4, 12, 43, 46, 52, 53B, 54, 56, 59; Schedule 1 Part 3 paragraphs 85 to 99B; definitions of Virtual Asset, Accepted Virtual Asset and Fiat-Referenced Token.
- Income Tax Act 2025 (Law No. 6 of 2025): s. 13(1)(za) (dividends of GMC-resident companies); s. 13Y (founders company; s. 13Y(5) no approval after 31 December 2030; s. 13Y(8) fifteen-year cap); s. 43(1)(a) (15% company rate); s. 43(1)(ba) (0% for non-citizen individuals to 31 December 2030); s. 43D (strategic and development company; s. 43D(4) no approval after 31 December 2030; s. 43D(7) twenty-year cap).
- Companies Act 2025 (Law No. 1 of 2025), s. 4A (references to "$" mean United States dollars).
- Application of Laws Act 2024 (Law No. 1 of 2024), ss. 3 to 5, Schedule A (applied Singapore enactments) and Schedule B (applied Abu Dhabi Global Market financial services rulebooks).
- GEN Rulebook 2026, Chapter 2 (Principles for Licensed Firms); Chapter 5 (application for a Financial Service Licence).
- Royal Charter No. 1 of 2024, Articles 1, 3, 4 and 7.
- Constitution of the Kingdom of Bhutan, Article 5 (minimum 60% forest cover).
- Transparency International, Corruption Perceptions Index (most recent editions).